More Homes for Sale Isn’t a Warning Sign – It's Your Buying OpportunityMaybe you’ve heard that the number of homes for sale has reached a recent high. This might lead you to

Dated: March 1 2024
Views: 64
If you’re holding out hope that the housing market is going to crash and bring home prices back down, here’s a look at what the data shows. And spoiler alert: that’s not in the cards. Instead, experts say home prices are going to keep going up.
Today’s market is very different than it was before the housing crash in 2008. Here’s why.
It was much easier to get a home loan during the lead-up to the 2008 housing crisis than it is today. Back then, banks had different lending standards, making it easy for just about anyone to qualify for a home loan or refinance an existing one.
Things are different today. Homebuyers face increasingly higher standards from mortgage companies. The graph below uses data from the Mortgage Bankers Association (MBA) to show this difference. The lower the number, the harder it is to get a mortgage. The higher the number, the easier it is:
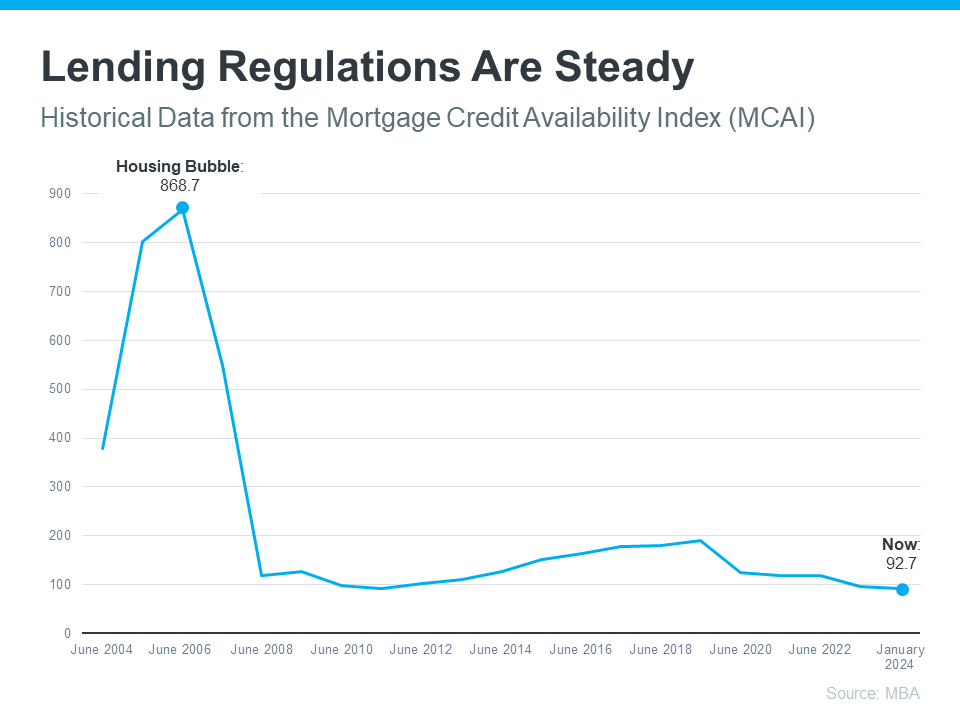
The peak in the graph shows that, back then, lending standards weren’t as strict as they are now. That means lending institutions took on much greater risk in both the person and the mortgage products offered around the crash. That led to mass defaults and a flood of foreclosures coming onto the market.
Because there were too many homes for sale during the housing crisis (many of which were short sales and foreclosures), that caused home prices to fall dramatically. But today, there’s an inventory shortage – not a surplus.
The graph below uses data from the National Association of Realtors (NAR) and the Federal Reserve to show how the months’ supply of homes available now (shown in blue) compares to the crash (shown in red):
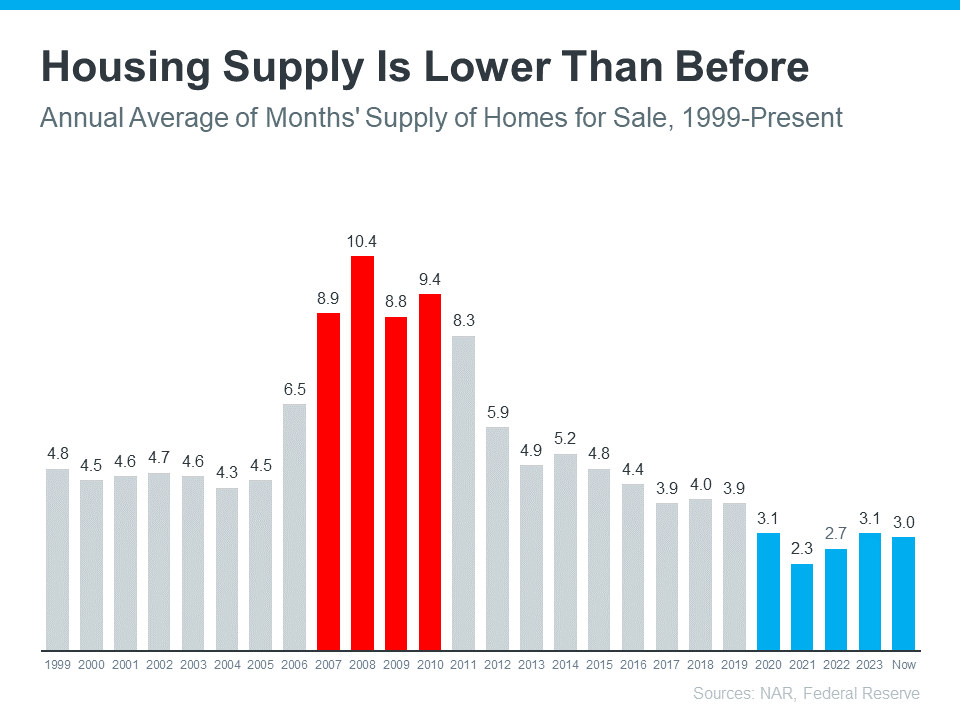
Today, unsold inventory sits at just a 3.0-month supply. That’s compared to the peak of 10.4 month’s supply back in 2008. That means there’s nowhere near enough inventory on the market for home prices to come crashing down like they did back then.
Back in the lead-up to the housing crash, many homeowners were borrowing against the equity in their homes to finance new cars, boats, and vacations. So, when prices started to fall, as inventory rose too high, many of those homeowners found themselves underwater.
But today, homeowners are a lot more cautious. Even though prices have skyrocketed in the past few years, homeowners aren’t tapping into their equity the way they did back then.
Welcome to my world of real estate, where my passion for helping clients like you find their dream home or navigate successful selling is more than just a profession—it's my purpose. I'm Marcus ....
Marcus Roth
More Homes for Sale Isn’t a Warning Sign – It's Your Buying OpportunityMaybe you’ve heard that the number of homes for sale has reached a recent high. This might lead you to
Housing Market Forecasts for the Second Half of 2025From rising home prices to mortgage rate swings, the housing market has left a lot of people wondering what’s next – and whether now
Why Today’s Foreclosure Numbers Aren’t a Warning SignWhen it feels like the cost of just about everything is rising, it’s only natural to wonder what that means for the housing
Curious about where the housing market is headed in 2025? The good news is that experts are offering some promising forecasts, especially when it comes to two key factors that directly affect your
 The data relating to real estate for sale on this web site comes in part from the Internet Data Exchange of the Greater Lehigh Valley REALTORS®. Real Estate listings held by brokerage firms (licensees) other than #firm are marked with the IDX logo and detailed information about them includes the name of the listing brokers.
The information being provided is for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers
may be interested in purchasing.
Data last updated September 25, 2026 4:07 PM UTC
Show More...
 ©2026 Georgia Multiple Listing Service All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may
be interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than The Brokers Realty Group Limited may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 25, 2026 4:05 PM UTC
Show More...
 The data relating to real estate for sale on this web site includes listings held by MLS-IDX Participants of the Internet Data Exchange program of the Multiple Listing Service of the Pocono Mountains Association of Realtors®. Listings marked with the Internet Data Exchange logo are not necessarily the listings of the owner of this web site. All listing data is the copyrighted property of the aforesaid Association and its MLS-IDX Participants with all rights reserved. The information contained
herein is believed to be accurate, but no warranty as such is expressed or implied.
Show More...
 © BRIGHT, All Rights Reserved
Information Deemed Reliable But Not Guaranteed
The data relating to real estate for sale on this website appears in part through the BRIGHT Internet Data Exchange program, a voluntary cooperative exchange of
property listing data between licensed real estate brokerage firms in which
participates, and is provided by BRIGHT through a licensing agreement.
The information provided by this website is for the personal,
non-commercial use of consumers and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Data last updated: September 25, 2026 2:34 PM UTC
Some properties which appear for sale on this website may no longer be available
because they are under contract, have Closed or are no longer being offered for sale.
Some real estate firms do not participate in IDX and their listings do not appear on this website. Some properties listed with participating firms do not appear on this website at the request of the seller.
Show More...
 Luzerne County Association of REALTORS® (LZCAOR) All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than The Brokers Realty Group Limited may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 25, 2026 4:06 PM UTC
 Susquehanna Valley Board of REALTORS® All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be
interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than The Brokers Realty Group Limited may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 25, 2026 4:14 PM UTC
Show More...
